Real Estate News You Can Use

You’ll find our blog to be a wealth of information, covering everything from local market statistics and home values to community happenings. That’s because we care about the community and want to help you find your place in it. Please reach out if you have any questions at all. We’d love to talk with you!

Oct. 5, 2026

Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.

Half the buyers out there are scared home prices are about to crash. The other half are hoping they will.

A recent survey from Clever found 58% of Gen Z buyers are actually rooting for a crash, just so homeownership feels within reach.

So, what do the forecasts actually say?

Every quarter, Fannie Mae surveys more than 100 housing experts on where prices are headed. The newest results are in. And spoiler alert: they’re not calling for a crash – not even the pessimists.

What the Newest Numbers Actually Say

The panel's latest forecast has prices climbing every single year through at least 2030.

The panel's average forecast is that prices will rise by 14.7% in the next 5 years. And here’s where it gets really interesting. If you split these experts into optimists and pessimists, even the pessimists still expect prices to increase about 6.6% by the end of 2030 (see graph below):
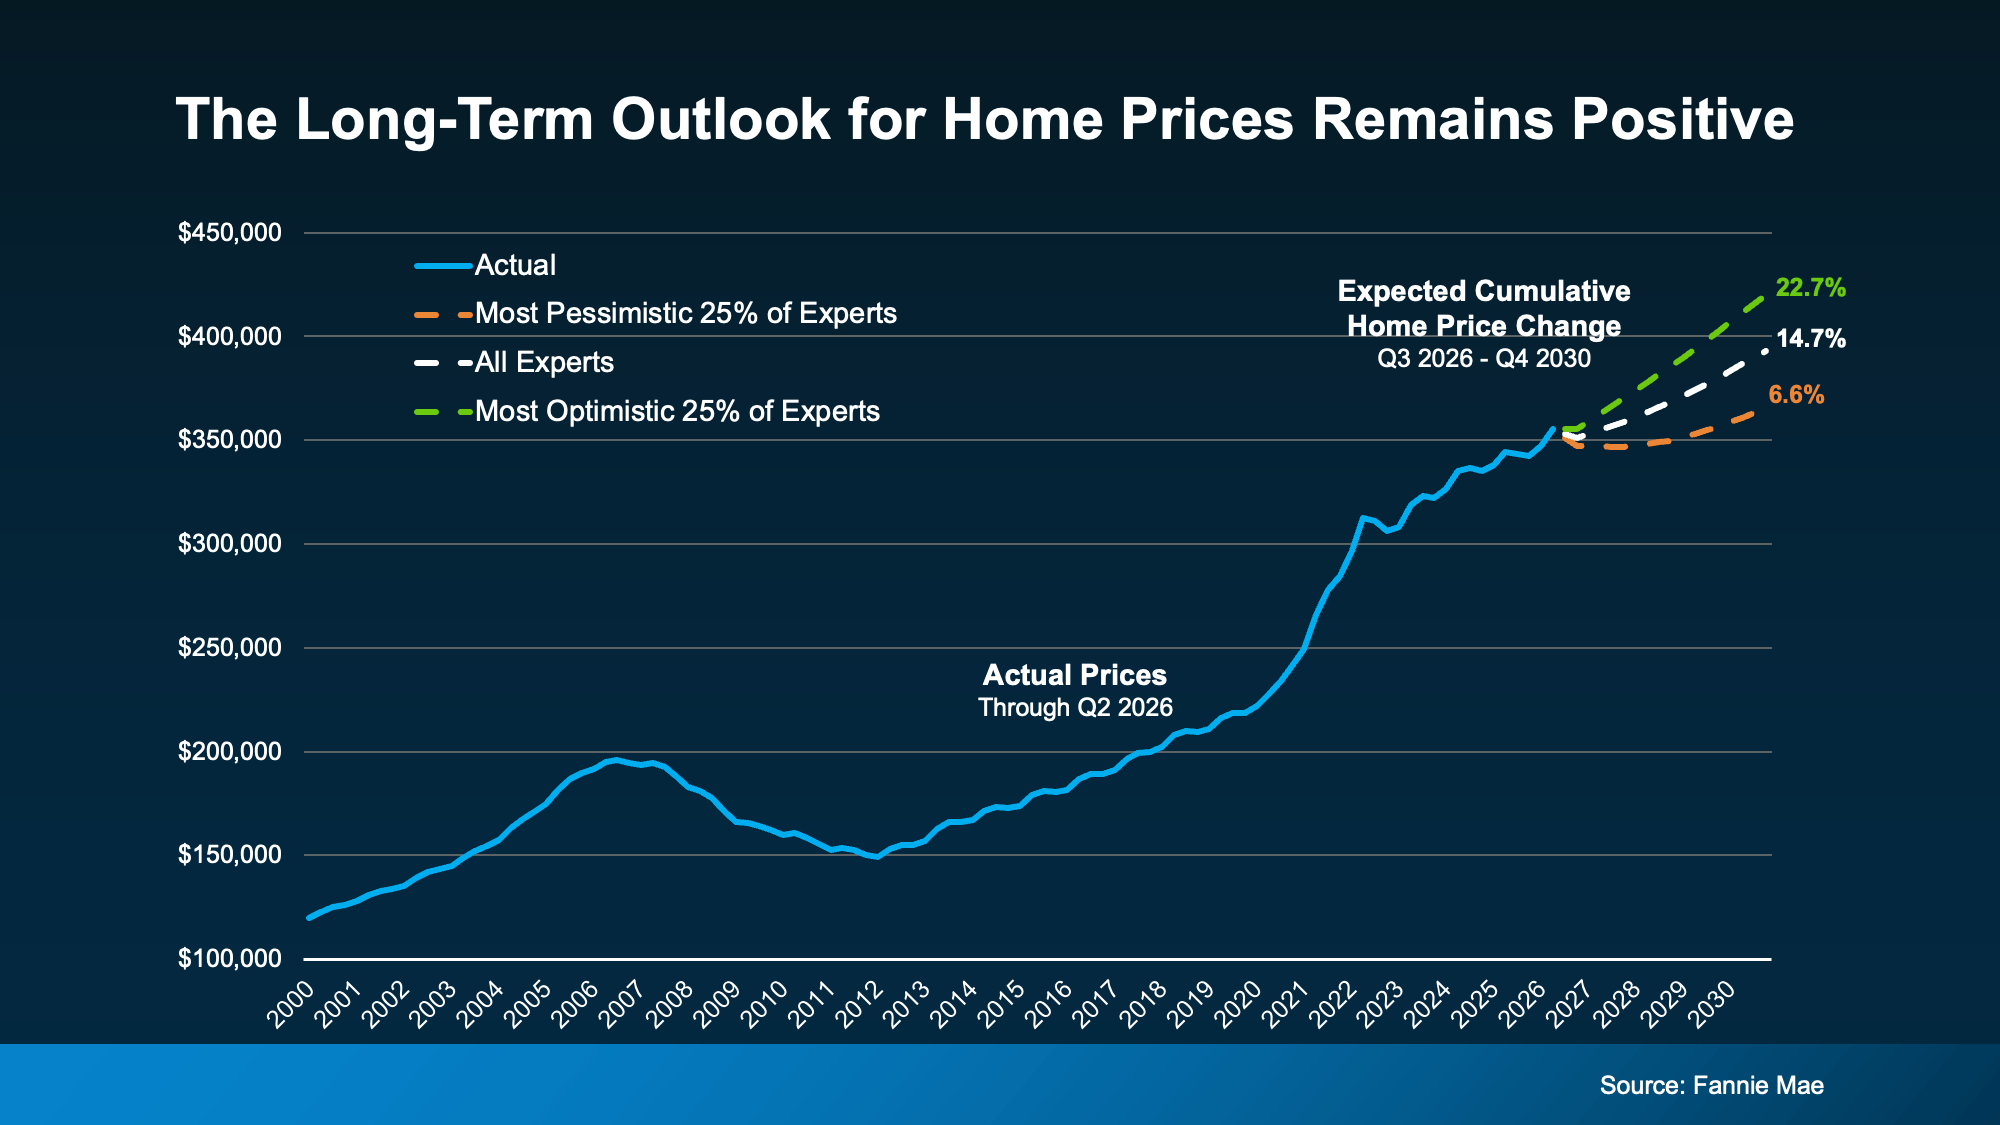
a graph showing the price of a home

The takeaway? If you've been waiting for prices to fall, you may be waiting a while.

One thing to keep in mind though – these are national numbers. Prices in your area could run a little hotter or a little cooler than this, so it helps to know what’s happening locally, too. But the big picture is prices aren’t crashing. Historically prices usually rise.

How This Quarter Compares to the Past

Here’s something you probably don’t realize. This survey runs 4 times every year, so you can track the panel's mood over time.

A year ago, the panel expected home prices to grow 2.1% this year. Now they’re forecasting 2.5%. That means the near-term outlook actually got more optimistic. But that’s only part of the story. The years after that shifted, too (see graph below):
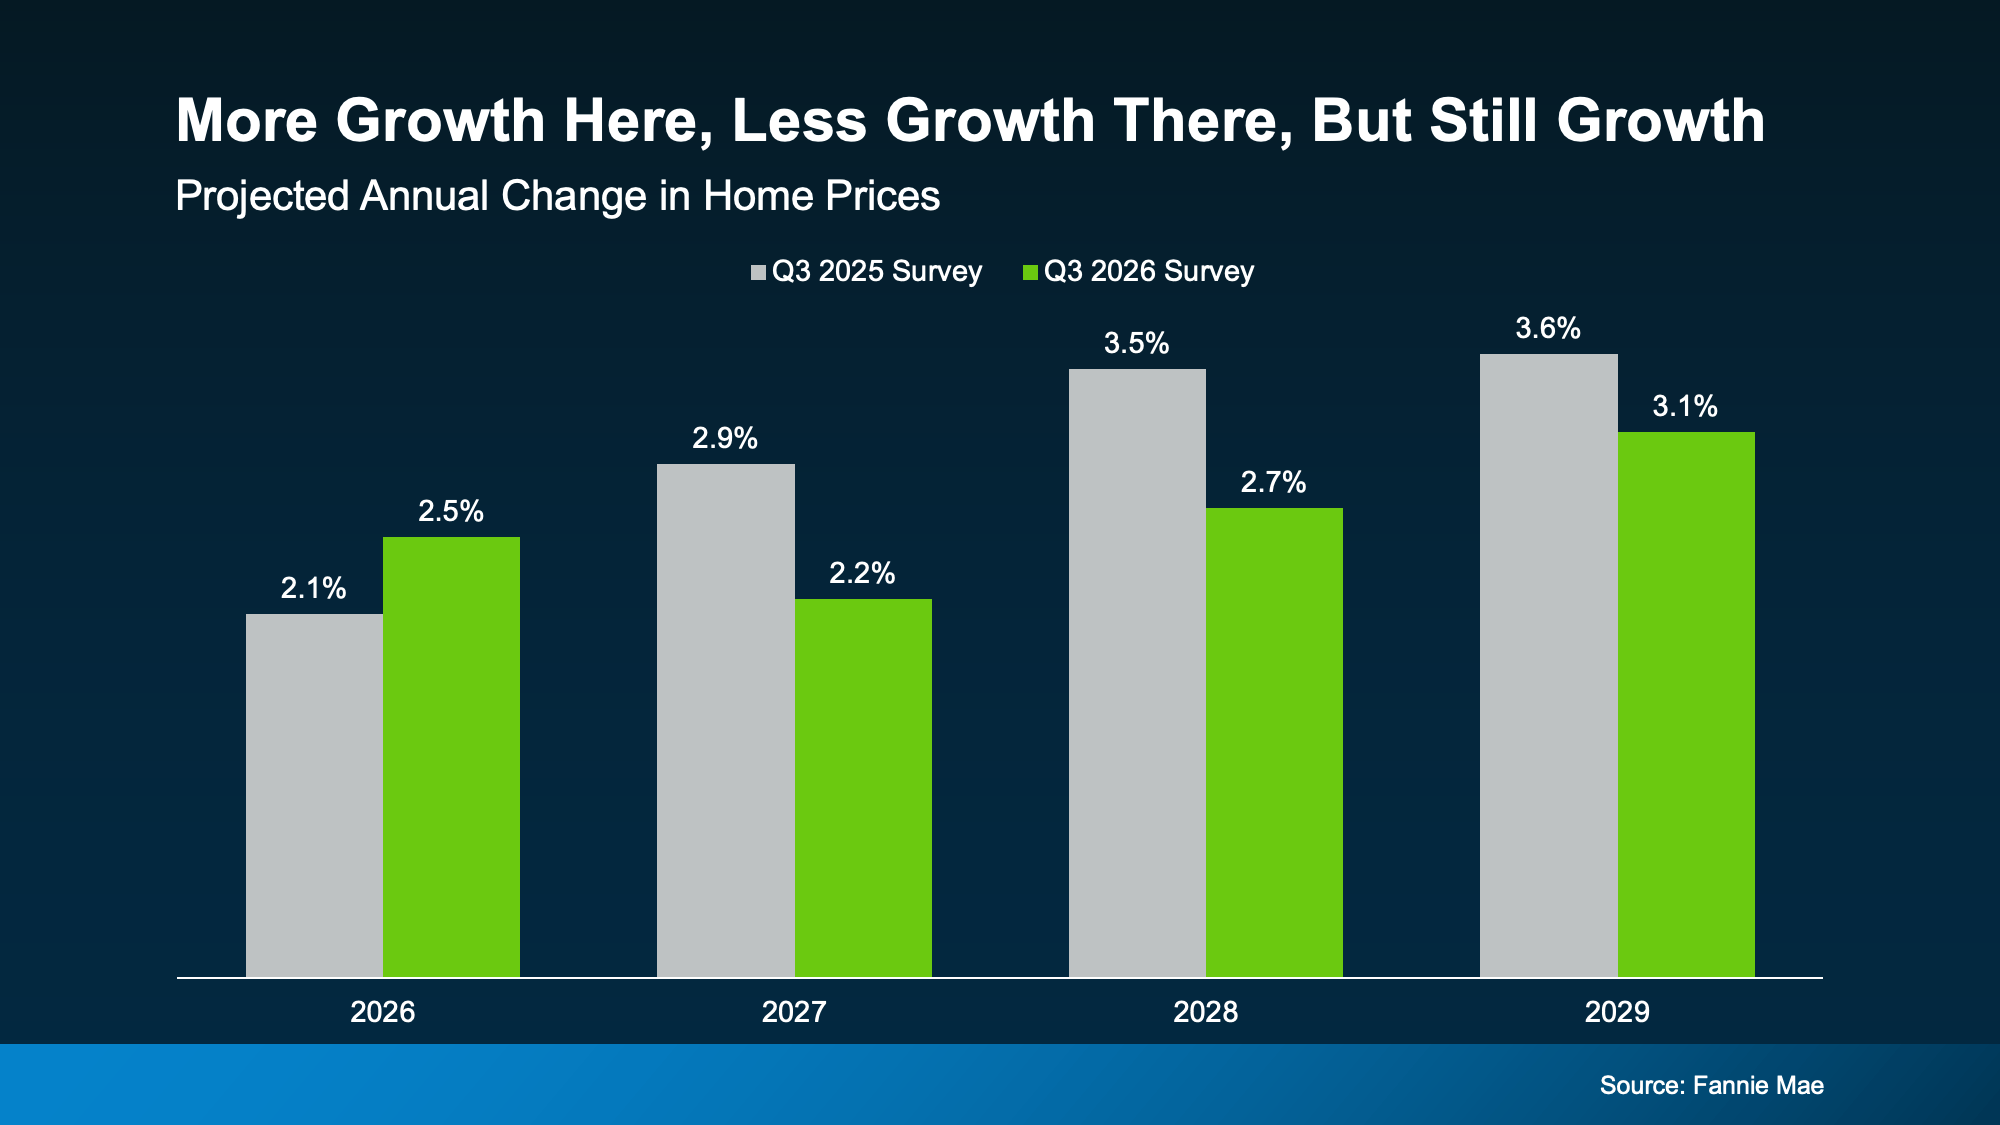
a graph of growth in a graph

Zoom out to 2027 through 2029 and the mood has cooled a bit. Each of those years is now expected to see a little less growth than the panel thought a year ago. That’s likely a reflection of where we are right now with everything that’s impacting the housing market.

But again, the overall takeaway here is every bar shows an increase in prices – the size of that increase has just moderated due to some of the factors at play.

A slower climb isn’t a bad thing, though. It’s a sign the market is settling into a more normal pace after a few wild years.

A little more growth here, a little less growth there. What hasn't budged once is the idea that home prices will keep growing.

What It Means for Your Next Move

Now, percentages are great, but you probably care more about the actual dollars and cents of your move, so let’s graph that out, too.

Run the numbers on a $400,000 home bought in January, and the panel's latest forecast puts you up about $58,000 in equity in 5 years just from price growth (see graph below):
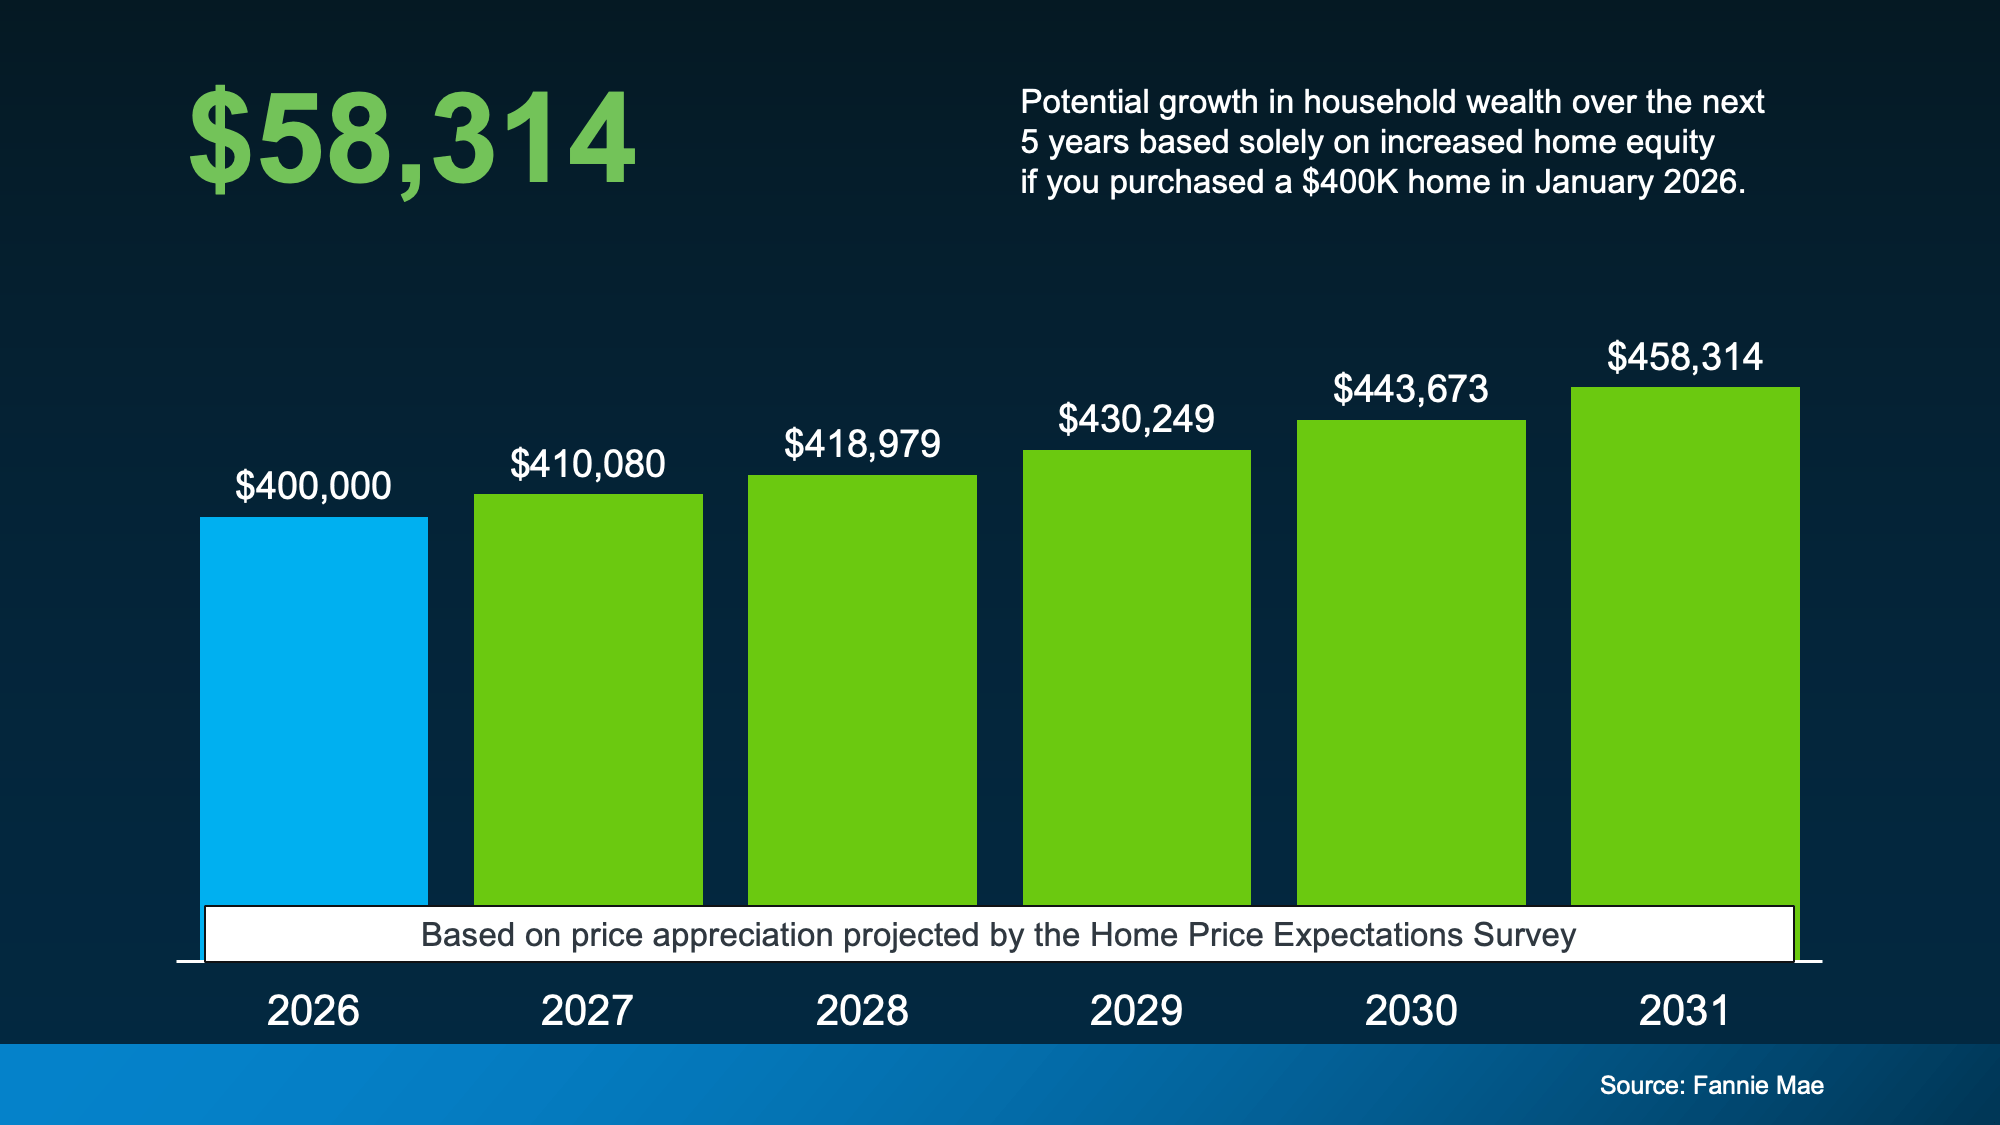
a graph of growth in a number of green squares

That’s real wealth you could be building while others sit on the sidelines, waiting for a crash the experts don’t see coming. And with prices expected to keep rising, waiting could mean paying more for the same home later.

Bottom Line

Whether you're bracing for a crash or hoping for one, the verdict is the same – prices are still expected to rise, not fall. Let's talk about what that means for your market and your plans.
The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Buying, Selling
Oct. 5, 2026

The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.

You may have seen the headlines saying mortgage rates have climbed to the highest point since January 2025. And if that's left you reluctant to buy a home, here's what you need to remember… 

That's not necessarily the number you'd get. 

It's a common misconception that the rate you see in the headlines is the same one you'd get when you buy. The truth is, mortgage rates shift often, and the rate you actually end up with can vary a lot from what you may see or hear about. 

What Determines Your Real Rate? 

Advertised rates and “real rates” aren’t always the same. That’s because real rates are based on your specific situation, which includes your overall finances and goals. The rates you see in the headlines can’t possibly reflect that. 

That’s why only a lender can tell you what your real rate will be. To figure out your unique number, they’ll look at:

  • Your credit score: Your credit score includes your payment history (if you’ve made late payments – and how often), credit utilization (are your accounts maxed out, or do you have available credit?), and the length of your credit history (how long have your accounts been open?). For example, someone with an exceptional credit score may qualify for a better rate.

  • Your debt-to-income ratio (DTI): This is calculated by dividing your monthly debt payments by your monthly income before taxes to come up with a percentage. The higher your DTI, the higher your rate could be.

  • The down payment size and Loan-to-Value (LTV): Your down payment is the percentage of the home’s price you will put down. The LTV is the percentage of a home’s sales price that equals your mortgage. 

  • The type and term of loan program options: Your loan officer will walk you through different loan options based on what you qualify for. Mortgage rates can vary between different loan products and programs. 

Even after you find a home you love, other things can have an impact too. For example:

  • A mortgage rate buydown: This helps you get a lower mortgage rate, and by extension, a lower monthly payment, by paying an upfront cost. Sometimes a seller, builder, or another party may even offer to cover that cost themselves as an incentive for you to buy.

  • Seller concessions: Sellers are allowed to pay buyer closing costs according to most loan program guidelines. Seller-paid closing costs can add up to thousands of dollars, which can free up some cash for you to increase your down payment, pay down debt, or make other financial adjustments to try to get a better rate. 

There’s a lot that can ultimately have an impact on your actual rate. 

Your First Step? Getting Pre-Approved.

If you want to know if your number could be higher or lower than the headlines on social, you need to talk to an expert. A simple conversation with a loan officer can help you determine when you’ll be ready to buy, how much you can borrow, and of course, what your real rate will be. 

Your lender may recommend a pre-qualification and pre-approval:

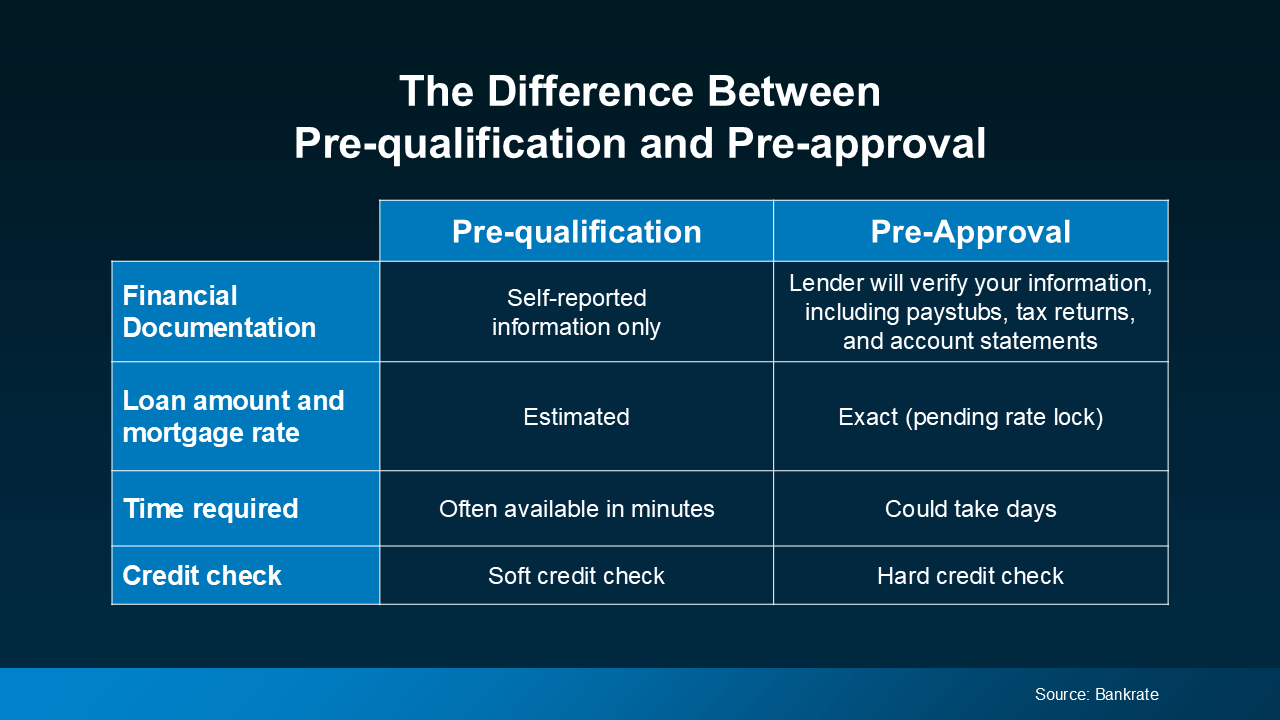
  • Pre-qualification is a general estimate of what you might be able to borrow based on self-reported information. 

  • On the flip side, pre-approval is actually a conditional commitment from a lender based on verified information. 

Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why:

a blue and white chart with white text

How To Get Ready for the Conversation

Ask your lender what documents you’ll need to gather for that conversation. And keep these questions in your pocket too. They’re good things to go over when you talk: 

  • What will I gain or lose by waiting to buy a home for 3, 6, or 12 months? 

  • Will I get any tax advantages by buying a home - and what are they? 

  • What's the benefit of buying a home and starting to build equity now versus waiting? And how does that impact my finances in the long run?

  • How will rate changes in either direction affect me?

Once you find out your rate, maybe you can buy now. Or maybe you still need to wait. But at least you’d know your options and can make an informed decision.  

Bottom Line

Headlines and social media make today’s rates sound high. But you have to remember, the rate you’re seeing online and your actual rate could be different. The only way to know what your rate could be is to talk to a trusted lender. 

With the right help, you can find out what your real rate is – and where it can take you.


The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Buying
Oct. 5, 2026

Why So Many Sellers Are Cutting Their Price Right Now

Price cuts are turning up everywhere right now, and they read very differently depending on which side of the deal you’re on.

Sellers tend to worry a cut means walking away with less than they hoped. Sometimes that’s true, but more often it just means the market moved faster than the listing did.

Buyers, for their part, often assume a cut means something’s wrong with the house. Most of the time, that’s not it.

This is what's actually driving all those price cuts, and why it matters no matter which side of the deal you're on.

42% of Homes for Sale Are Now Carrying a Price Cut

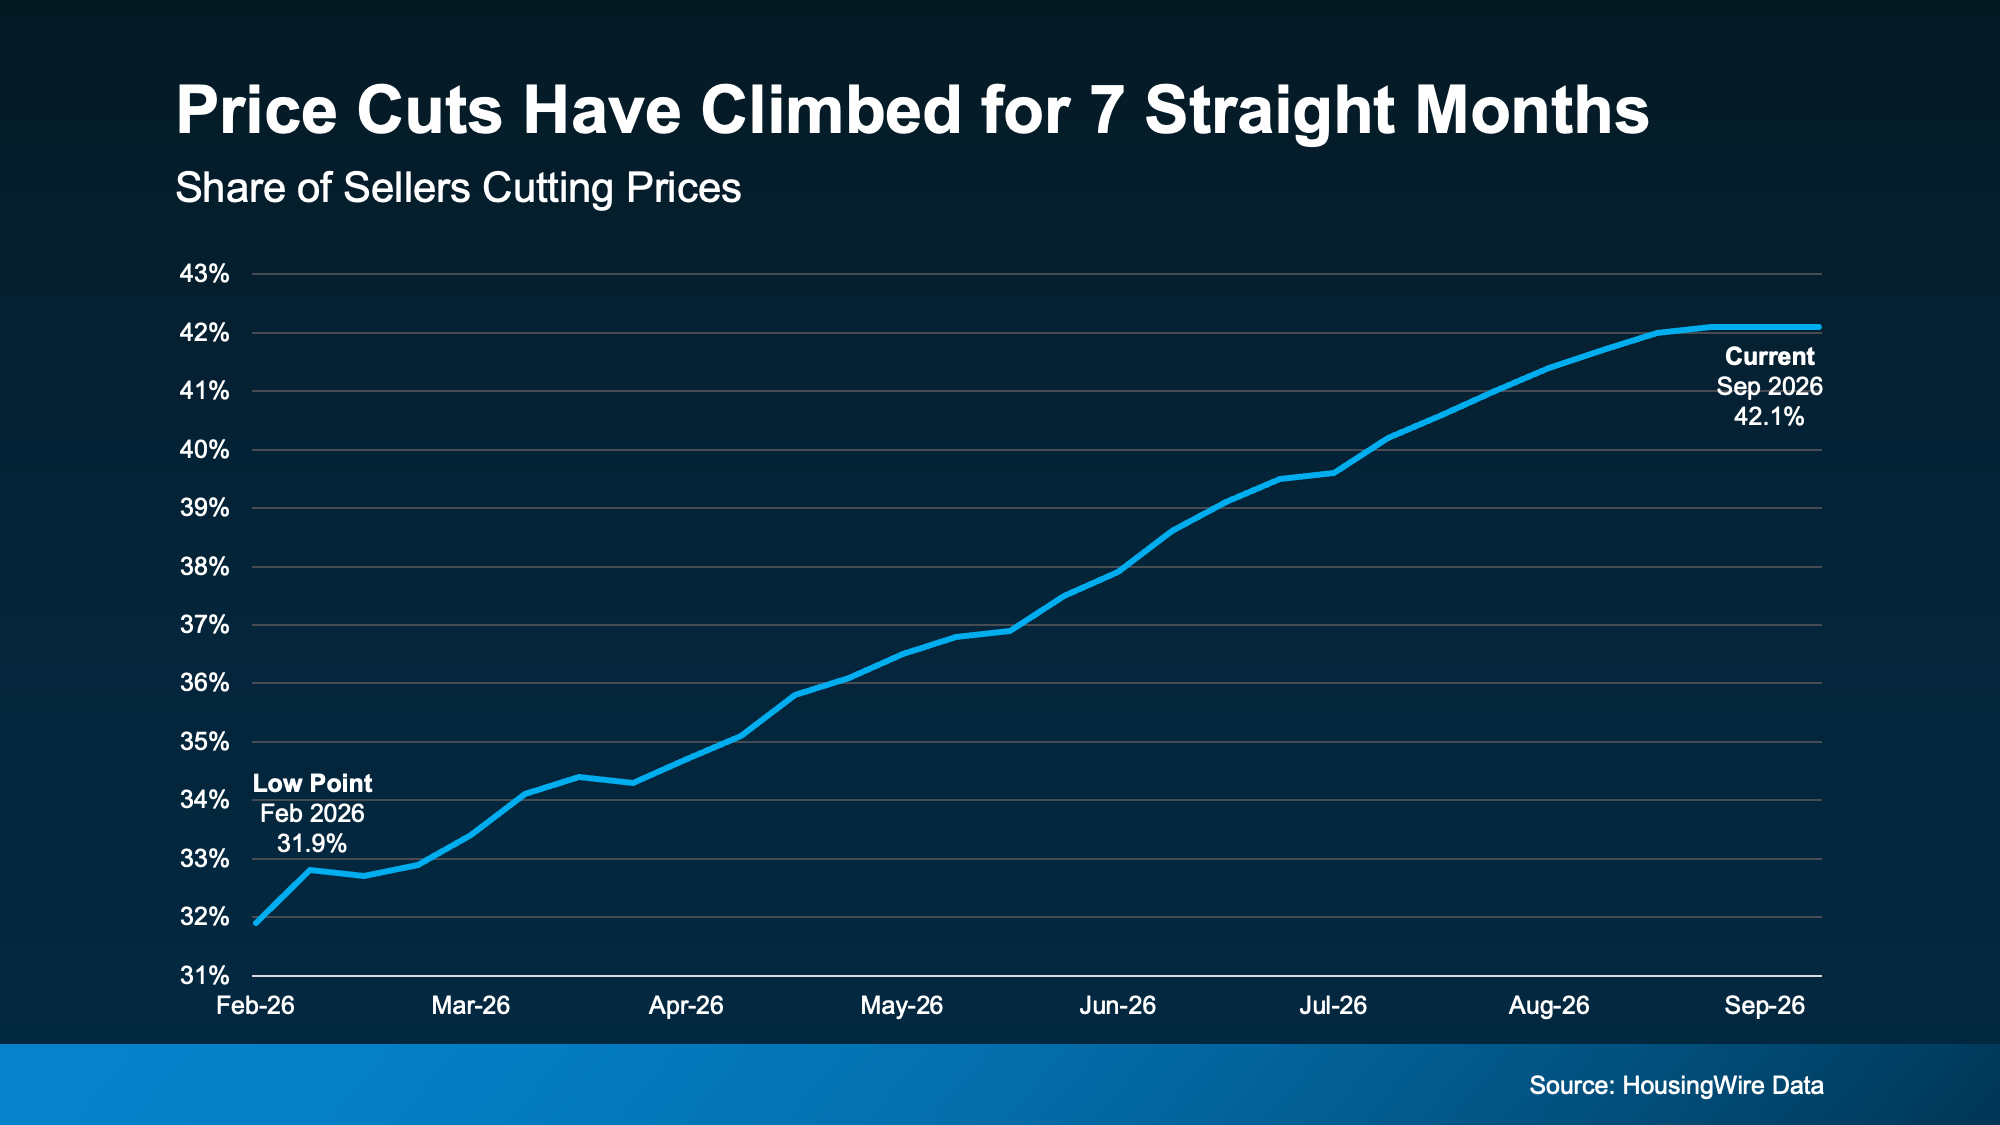
According to HousingWire Data, the share of sellers cutting their asking price has climbed every month for 7 straight months (see chart below):

a graph showing the growth of a straight month 

Today, more than 4 in 10 active listings have had at least 1 price cut, and the typical seller is cutting about $17,560 off their original number. 

Here’s why that’s happening. With rates still elevated and more homes to choose from, buyers can afford to wait for the right number. So, sellers who don’t start there often end up adjusting anyway.

What does that mean for you?

  • If you're selling, this isn’t a red flag. But it is a sign that pricing it right from day 1 is your best bet. Just know that the market's been shifting fast enough this year that sometimes even a well-priced house can fall behind within a matter of weeks. If that happens to you, dropping your price to catch up to where pricing actually stands today tends to bring in more buyers and helps you sell closer to true market value.

  • If you're buying, it's easy to assume a price cut means something's wrong with the house. But with cuts happening on more than 4 in 10 homes right now, the reality is sellers are just catching up to where the market already is. And with affordability still tight, that's exactly the kind of opening you need to get a better deal.

Why Sellers Are Adjusting Faster than Before

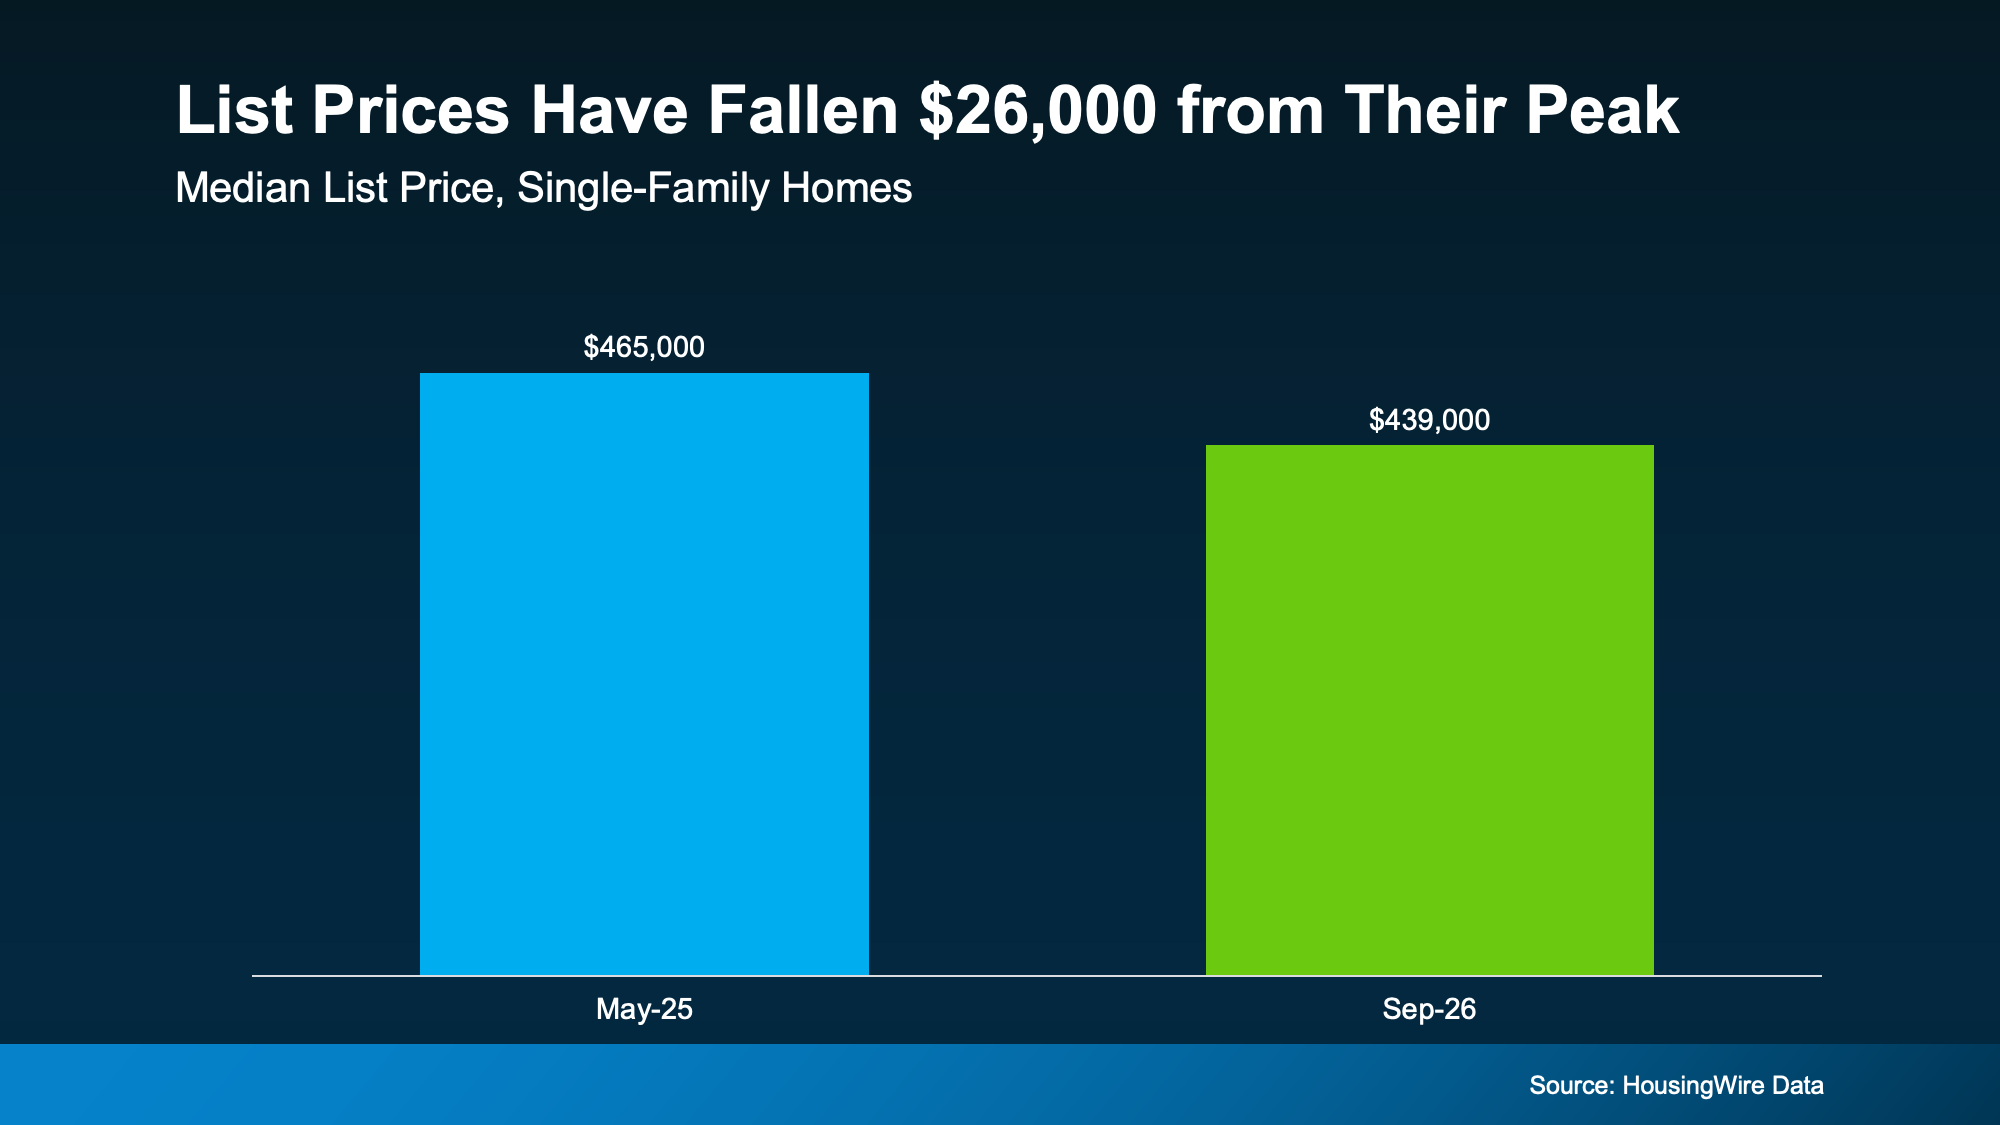
HousingWire Data also shows list prices are trending down nationally. That’s often a sign sellers are pricing more realistically from the start instead of listing high and getting stuck cutting later. List prices have fallen about $26,000 from last year's peak.

Some of that decline is seasonal, since list prices typically soften each winter before rebounding in the spring. So, expect asking prices to keep drifting a little lower before turning back around (see chart below):

a graph of a number of people 

Jake Krimmel, Senior Economist at Realtor.com, explains: 

“That is good news for buyers, who are seeing lower asking prices and more room to negotiate, but it is also good news for sellers: Pricing to today’s demand is helping homes move and keeping more transactions alive in a high-rate environment.”

Translation – with rates still elevated, buyers can only stretch so far. Sellers who meet them where they are instead of holding out for unrealistic prices are the ones actually getting to closing. And doing that up front is always better than chasing the market later.

Buyers, You’ve Got Room To Negotiate Again

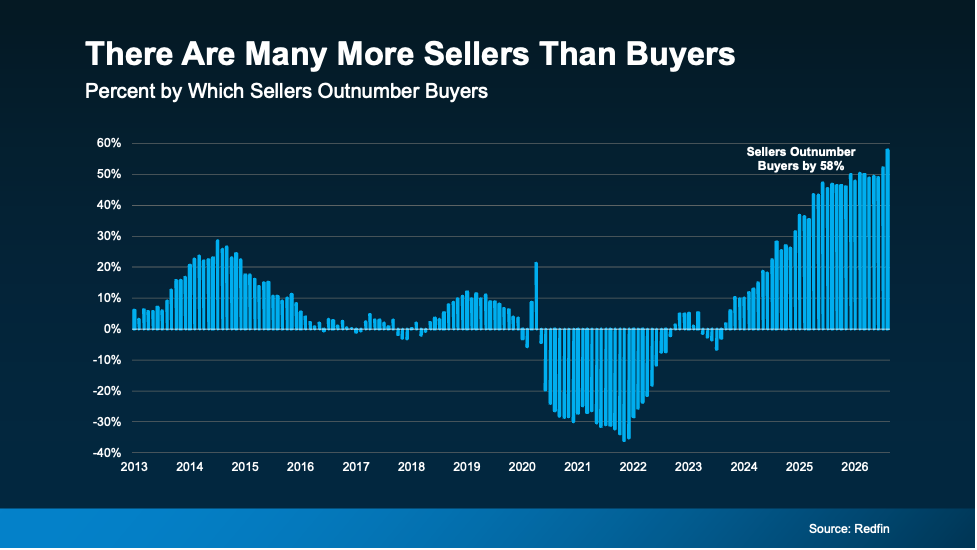
At the same time, Redfin data shows sellers now outnumber buyers by about 58%, the widest gap on record (see chart below):

a graph of sales 

That changes the power dynamics of the market – and impacts how homeowners should price their house. Nationally, about 7 in 10 markets now favor buyers or are trending that way.

  • For sellers, that means standing out matters as much as pricing. With more homes to choose from, buyers are comparing you directly against the competition. So, a little flexibility, like covering closing costs or being open on timing, can be what gets your house picked over another.

  • For buyers, it means more room to ask for a lower price, help with closing costs, repairs after inspection, or some combination of all 3. That’s especially true for homes that have already sat for weeks, where sellers are often the most willing to talk.

Bottom Line

Price cuts are a normal part of today’s housing market, and both buyers and sellers can use them to their advantage. Let's look at what's actually happening with prices in your neighborhood, so you know exactly where you stand before you list or make an offer.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Buying, Selling
Oct. 5, 2026

More Homes for Sale Now Than Any Time Since 2019

House hunting? You've got more homes to choose from than you've had in years. Right now, the number of homes for sale is the highest it's been since 2019. That's basically back to back to pre-pandemic normal – so there's more to pick from, and it's easier to find one that fits your budget. So, when you’re ready, let’s find your home and negotiate a deal you'll feel good about.


Posted in Buying
Oct. 5, 2026

What Higher Mortgage Rates Mean for Home Sellers

Higher mortgage rates don't just affect buyers. They can change what it takes to sell your house, too.

That's because today's buyers are paying close attention to affordability. And when rates rise, even a relatively small change can make a noticeable difference in their monthly payment. So, they're looking for ways to make the numbers work. And in some markets, new construction is giving them exactly that.

If you're planning to sell, that doesn't mean you can't compete. But it does mean you need to understand what builders are doing to win over buyers – and what options you have, too.

Builders Are Competing on the Monthly Payment

New construction has something interesting going for it right now. While existing-home sales  (homes that have previously been lived in) continue to struggle under the weight of higher mortgage rates, new-home sales are holding up a bit better.

In a recent interview, Logan Mohtashami, Chief Economist at HousingWire explains new-home sales are at an 8-month high and are now running around 2019 levels. On the flip side, existing home sales are lagging behind and fall about 1 million home sales short of 2019 levels.

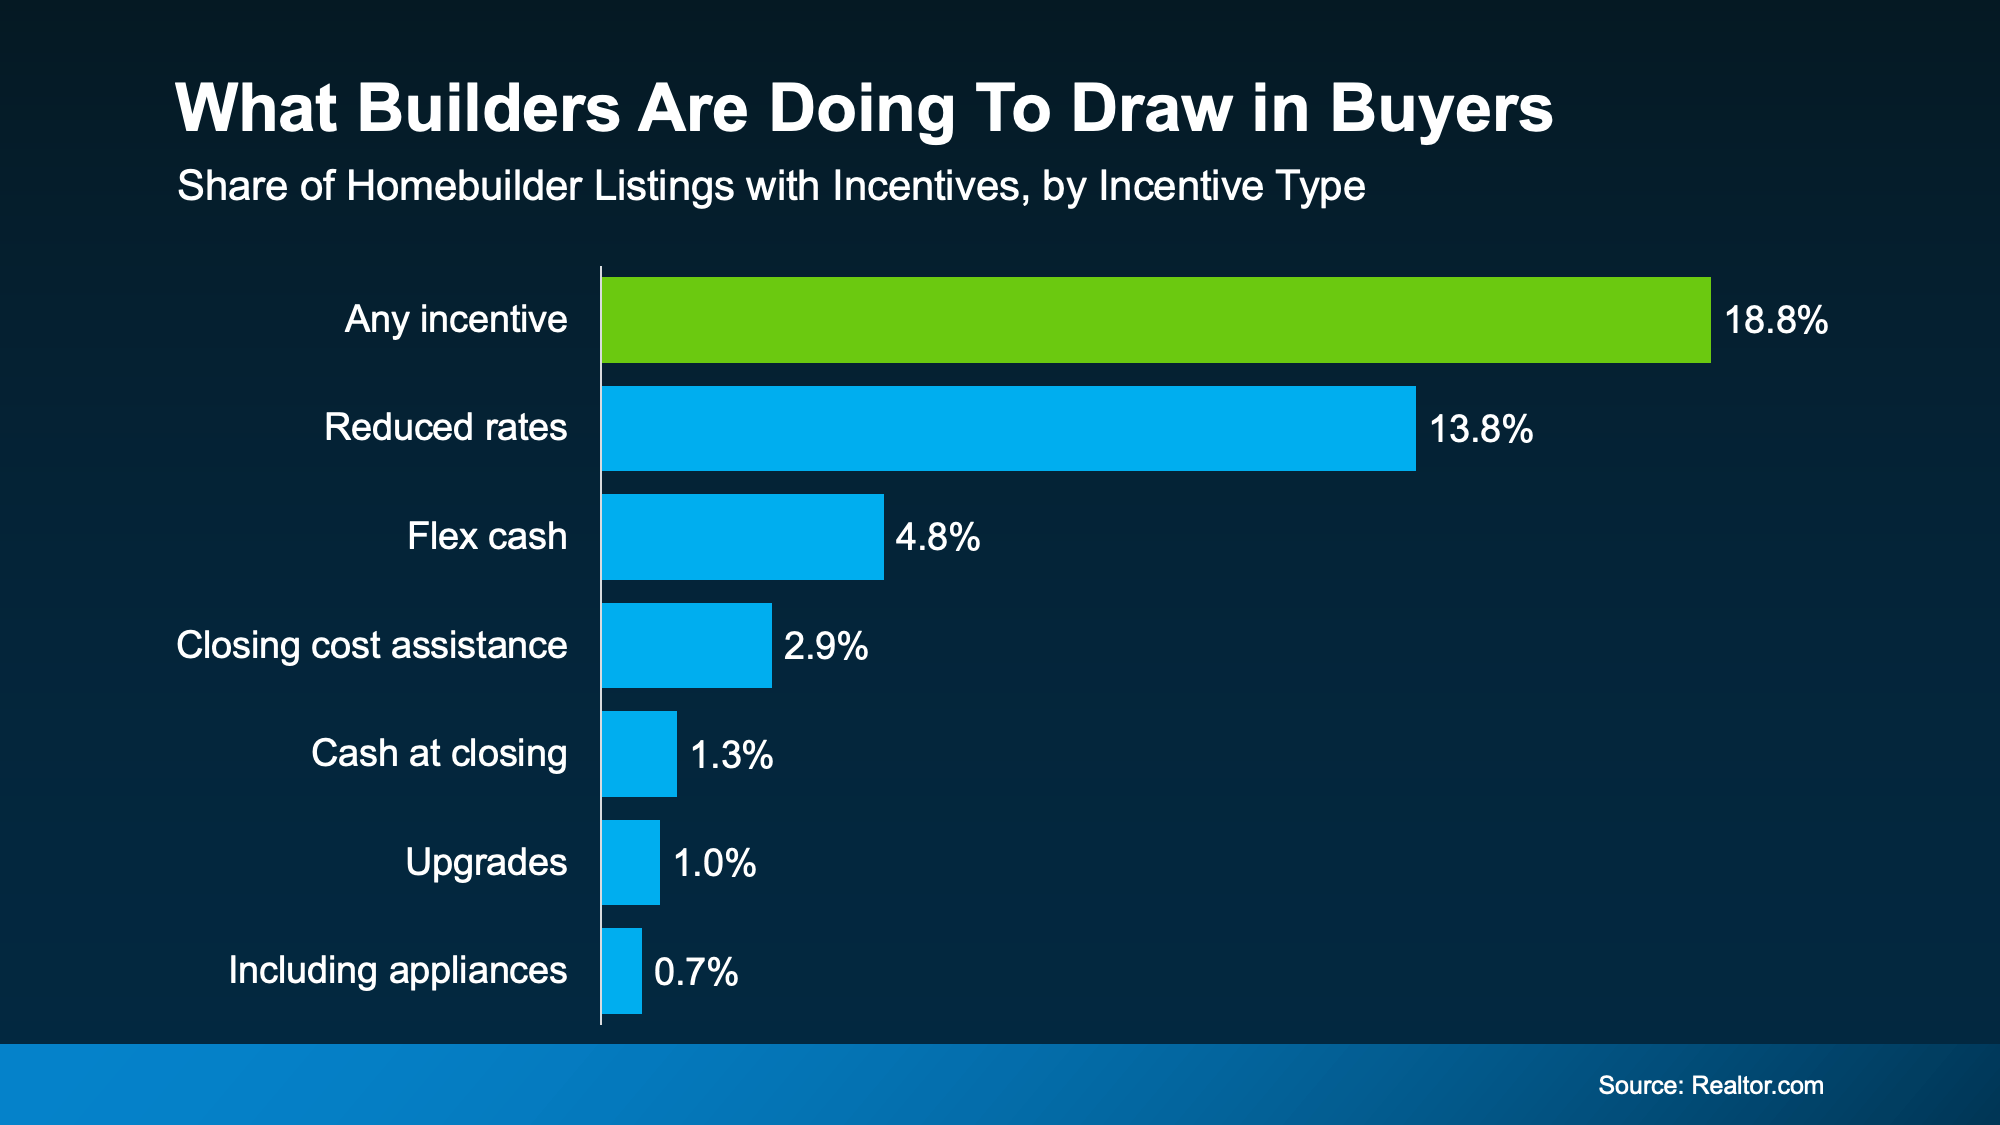
One big reason builders have been able to navigate higher rates differently is incentives. According to Realtor.com, nearly 1 in 5 (18.8%) newly built homes come with some kind of buyer incentive advertised up front:

a graph of a company's sales

The most common may surprise you. As the graph shows, many builders are offering reduced rates, sometimes through something called a mortgage rate buydown.

It’s essentially where they pay upfront costs to help buyers get a lower rate, and by extension, a lower monthly payment. It has obvious draws for buyers. For homebuilders, it helps them get their houses sold. So, a lot of builders see it as a win-win. That’s why reduced rates are a part of 13.8% of new home listings.

In some cases, builders are offering rates below 6%, maybe even far below 6%. And that can help buyers shave hundreds off their monthly payment. That's a big difference to a buyer who are feeling the pinch right now.

So, How Can Sellers Like You Compete?

First, don't assume a mortgage rate buydown is something only a builder can offer. Sellers can contribute toward a buyer's rate buydown too, depending on the loan and transaction. Does that mean you should offer one? Or that you have to if you want to compete? Not necessarily.

A buydown is just one possible lever. Depending on your market and the buyer, it may make more sense to negotiate on price, contribute toward your buyer’s closing costs, make repairs, or make sure your house stands out in ways a new build can't. That's why working with an agent who knows your local competition matters. Joel Berner, Senior Economist at Realtor.com, says:

“Sellers of existing homes are facing a lot of competition from the new-home space. . . so sellers should highlight the local amenities of their neighborhoods in contrast to the more suburban or exurban communities where many new homes are built.”

A great agent will do this naturally anyways. Knowing what makes your house different and showcasing that in your listing can help your house stand out. And remember, being open to making a few compromises or throwing in some concessions can make a bigger difference for buyers than you may think.

Today's Market Rewards Sellers Who Adapt

Builders have also been quicker to adjust their prices based on what buyers can actually afford and where demand is. That's putting pressure on the resale market in some areas. Robert Dietz, Chief Economist at the National Association of Home Builders (NAHB), explains:

“. . . existing homeowners now have to do the price discovery that builders have been doing since 2022.”

That's an important message if you're hoping to sell.

You don't automatically need to slash your price or offer a big concession. But you do need to price and market your house based on what buyers can pay today – not what sellers could get a few years ago.

And remember, this varies tremendously by location. New construction represents a much bigger share of the competition in some markets than others, and builder incentives aren't equally common everywhere. So, lean on an agent to see how big of a factor builders are in your area.

Bottom Line

Higher mortgage rates are making buyers more cost-conscious. Builders know that, and many are responding with reduced rate, closing-cost help, price reductions, and other incentives.

If you're thinking about selling, let's look at what buyers are getting from other homes in our area – including new construction – and make sure your house is positioned to compete.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Selling
Oct. 5, 2026

Two Moves That Can Get You Into Your First Home Sooner

For a lot of first-time buyers, owning a home can feel perpetually a few years out of reach. Saving for a down payment takes time, and each year you spend renting can make owning feel further off.

But buying your first home doesn’t have to happen to feel like a far away goal. Two choices you control can bring your first home years closer, even with affordability as tight as it is right now.

How Long Buying Really Takes

First, one quick definition. "Breaking even" is the point where owning has cost you about the same as renting would have over the same period. And after that point, owning starts to cost less than renting. Kara Ng, Senior Economist at Zillow, puts it this way:

"Buyers should think about not just when they can afford to buy, but how long they'd need to stay before owning makes more financial sense than renting."

So how long does reaching that point usually take? And what are the shortcuts? Let’s do the math.

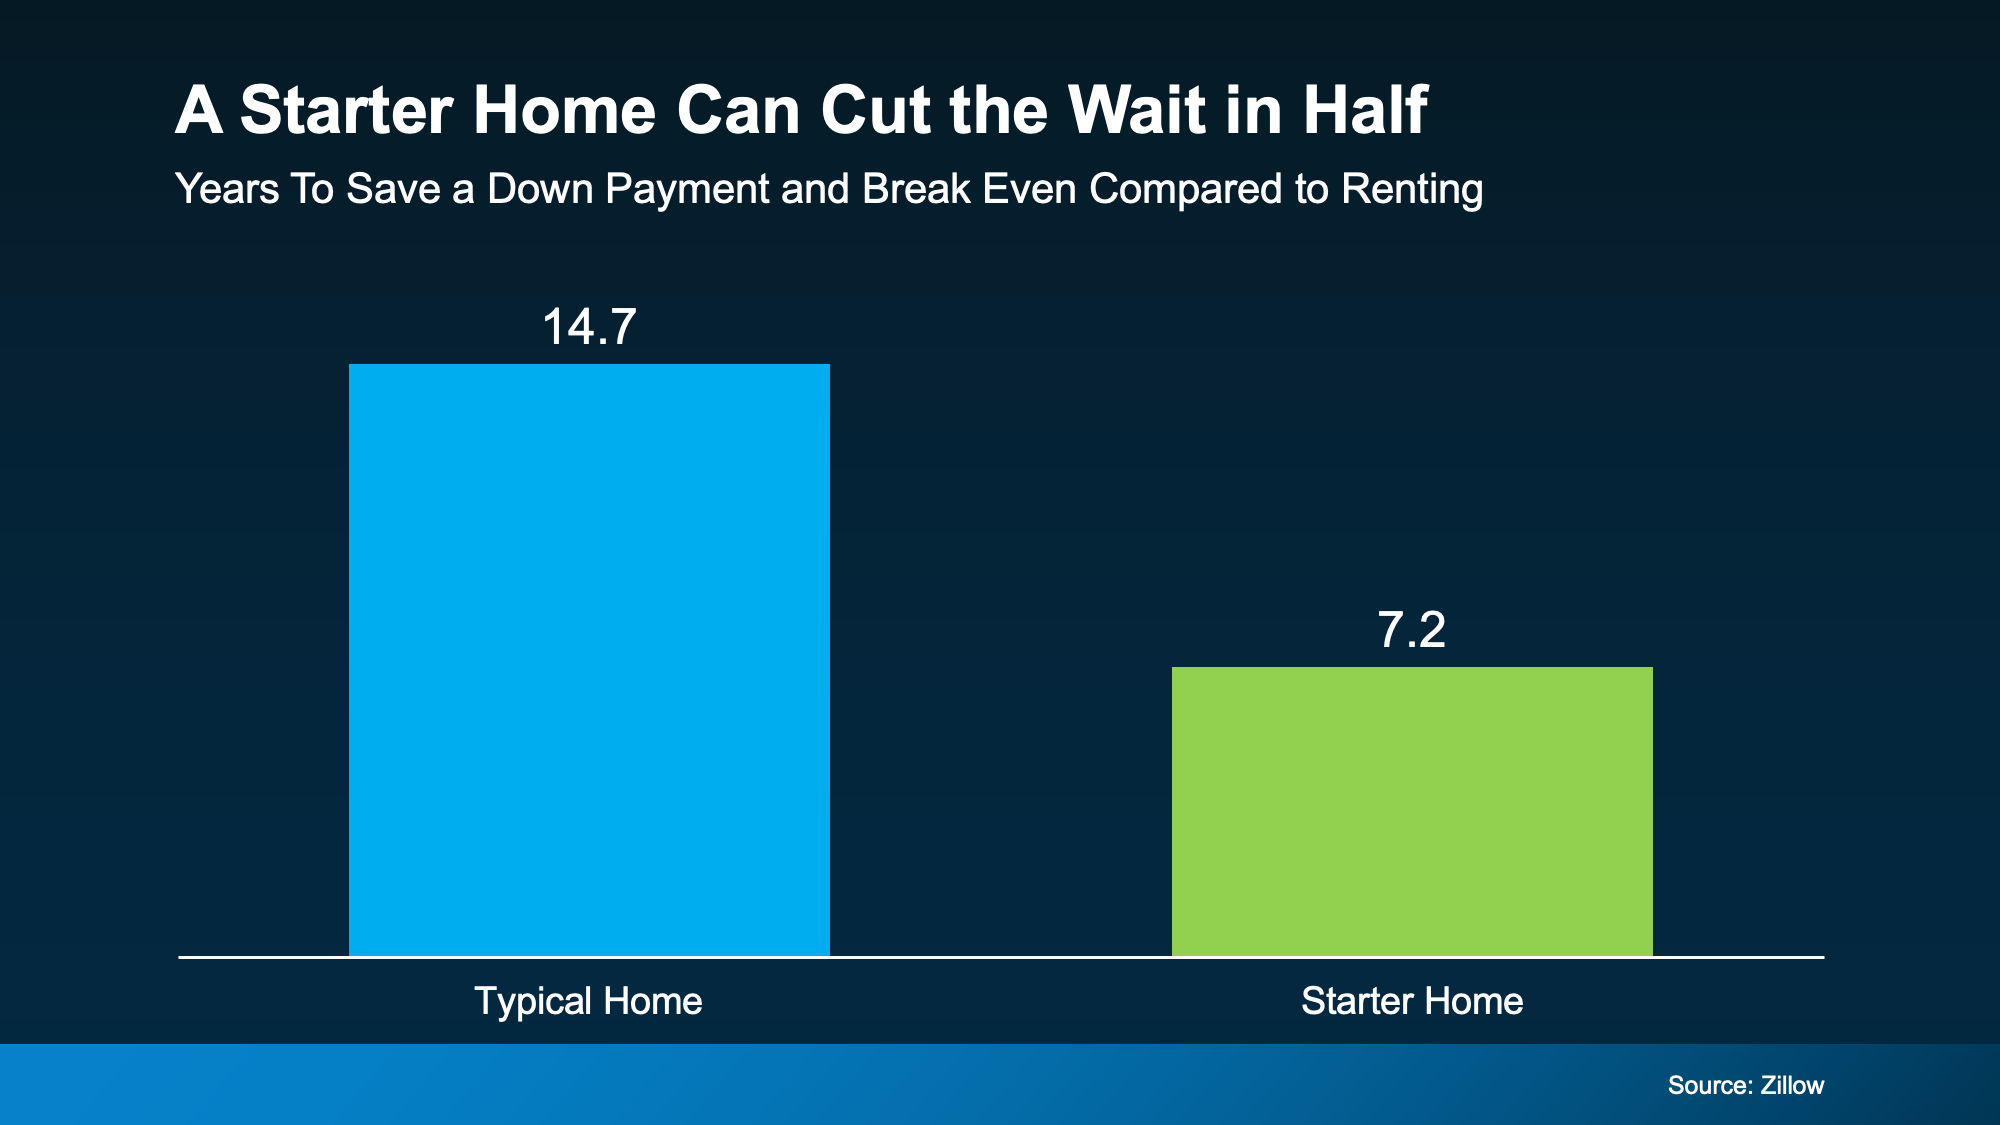
According to Zillow, it usually takes about 8.5 years to save for a 20% down payment, then roughly 6.2 more years before owning costs the same as renting. Together, that's just under 15 years. But that math relies on two assumptions: that you're buying a mid-priced home, and that you're putting 20% down. 

Change either one and your timeline gets shorter. Change both and it can shrink fast. It also varies widely by market, since local prices and rents are different depending on where you live. 

A Starter Home Can Get You There Twice as Fast

A starter home usually means a home in the lower third of local prices. They’re often condos, townhomes, or single-family homes a little smaller or older than others in the area. 

Choosing one over a mid-priced home can cut your wait down by a lot. And while that might sound obvious, you may not realize just how much it shortens your timeline. Because if you’re buying a more affordable home, you don’t have to save up as much or as long.

Zillow found that nationwide, a starter home takes half the time – about 7.2 years – to save for and come out ahead on, compared with renting (see graph below):

a graph of a number of squares

That works out to about 4.6 years to save and 2.6 years to break even. It won't erase every affordability challenge, but it can take years off the wait. And if you’ve already been saving for a while, it could get you closer to making it a reality.

You Usually Don't Need To Put 20% Down

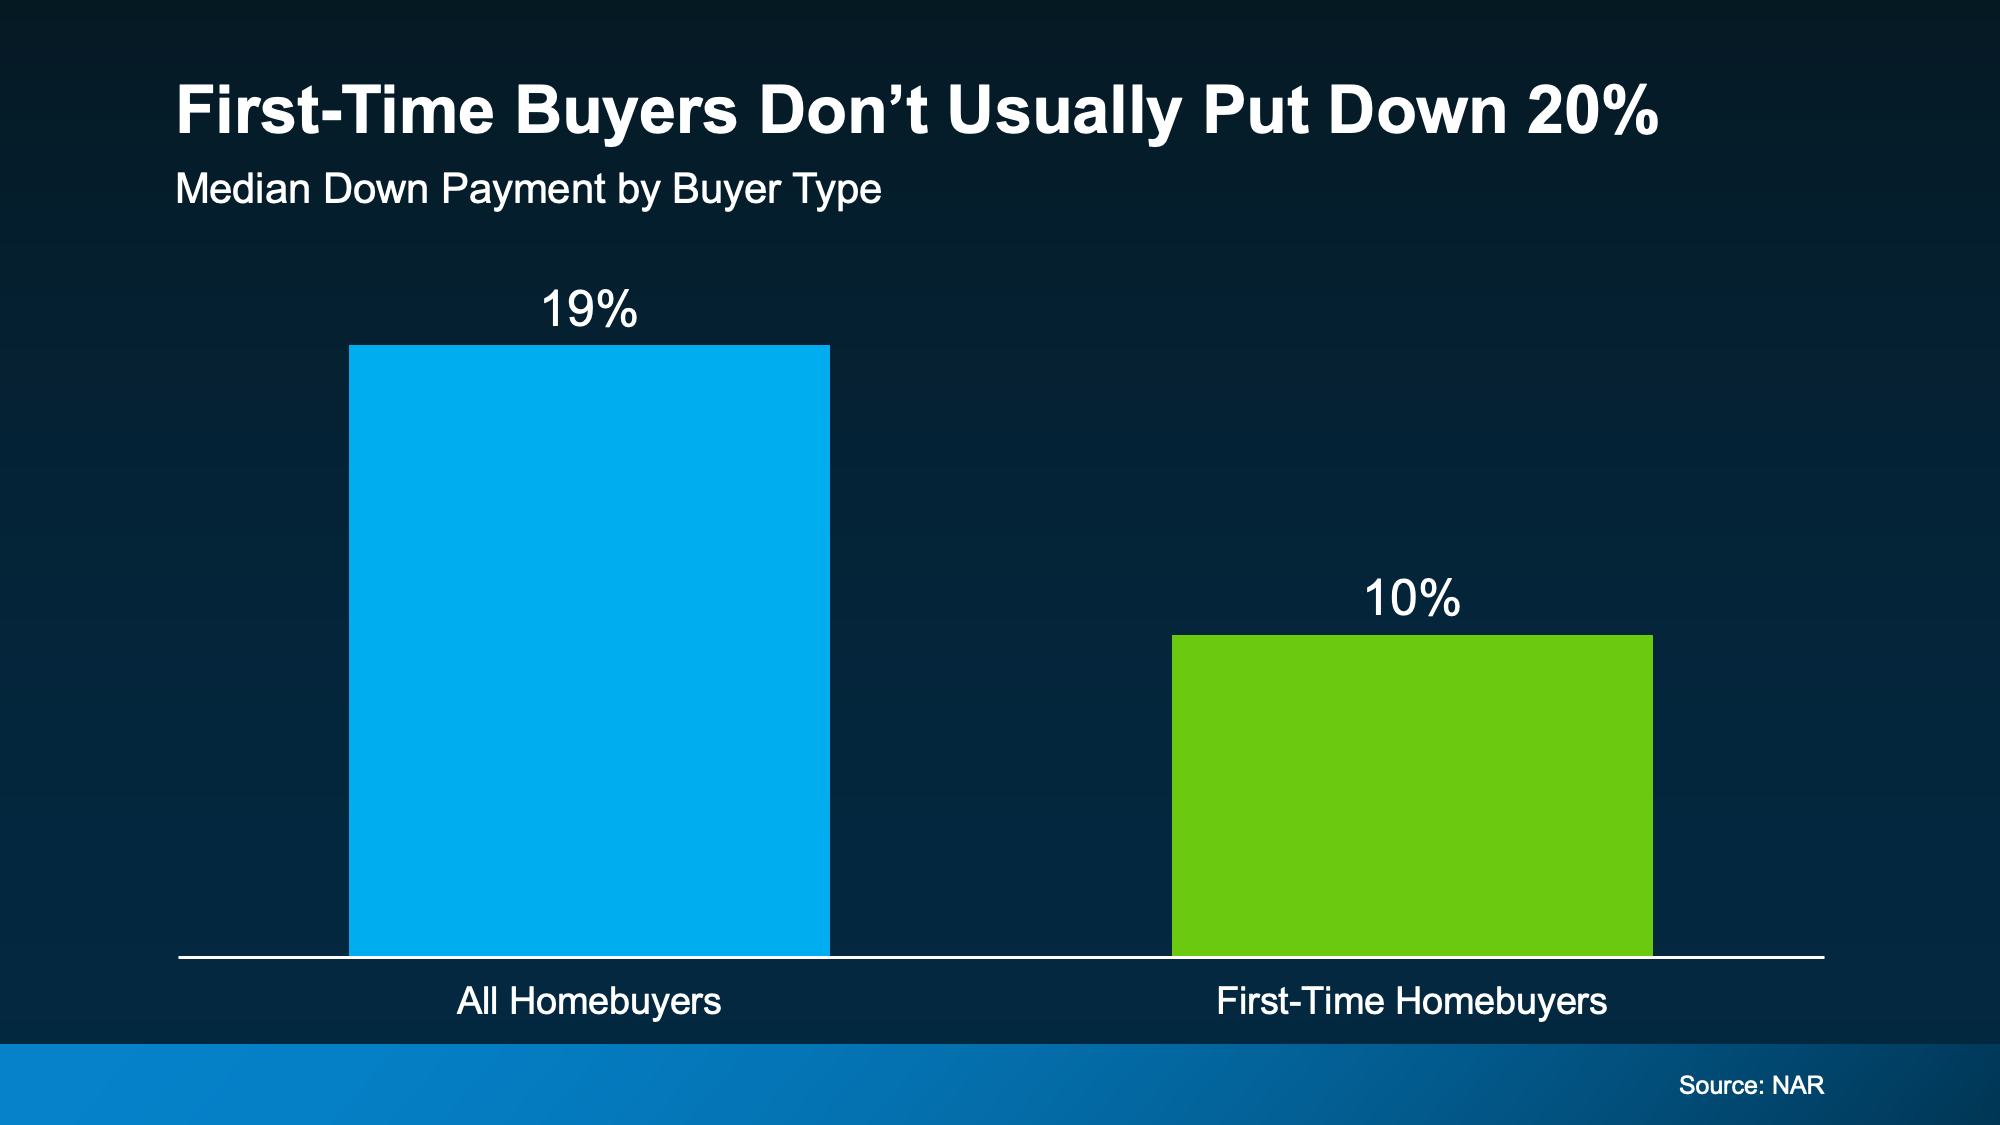
You, like many first-time homebuyers, might assume you need a 20% down payment to even consider buying. But a lot of the time, you don’t. 

Most first-time buyers don't put down anywhere near that. The National Association of Realtors shows the median down payment for first-time buyers is 10% (see graph below):

a graph of a sales report

And the minimums go lower still. Some buyers put down as little as 3% on a conventional loan or 3.5% on an FHA loan, and eligible veterans or buyers in certain rural areas can put down nothing at all.

There's help with the upfront costs of buying, too. Down Payment Resource counts 2,746 assistance programs nationwide, and some are even stackable:

"Some homebuyers can layer multiple sources of assistance to reduce their upfront costs. Layering means combining more than one eligible source of funding as part of your home purchase."

Put those together – a lower price point, a smaller down payment, and help covering it – and the years you thought you needed start to come down.

Bottom Line

Your first home may not be as far off as it feels. When the numbers make sense for you, buying a starter home and putting down less than 20% can get you there years sooner. 

Want to see which starter homes in our area could fit your budget? Let's connect.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.

Posted in Buying
Sept. 7, 2026

Sellers Are Cutting Prices To Meet Buyers Where They're At

You're scrolling through listings on your phone and everything looks good until you see the price (or the estimated monthly payment). Then you close the app. 

Because even if you love the house, the numbers feel impossible. But here's the thing.

Nationally, there are more homes sitting on the market than there are people out there looking. And when sellers need buyers more than buyers need sellers, that shows up in the price.

Lower asking prices. More price cuts. And homes priced for what buyers can actually afford – not what sellers hope someone might pay.

And it may be enough to make buying more doable than you’d think. 

4 Out of 10 Sellers Are Cutting Their Price 

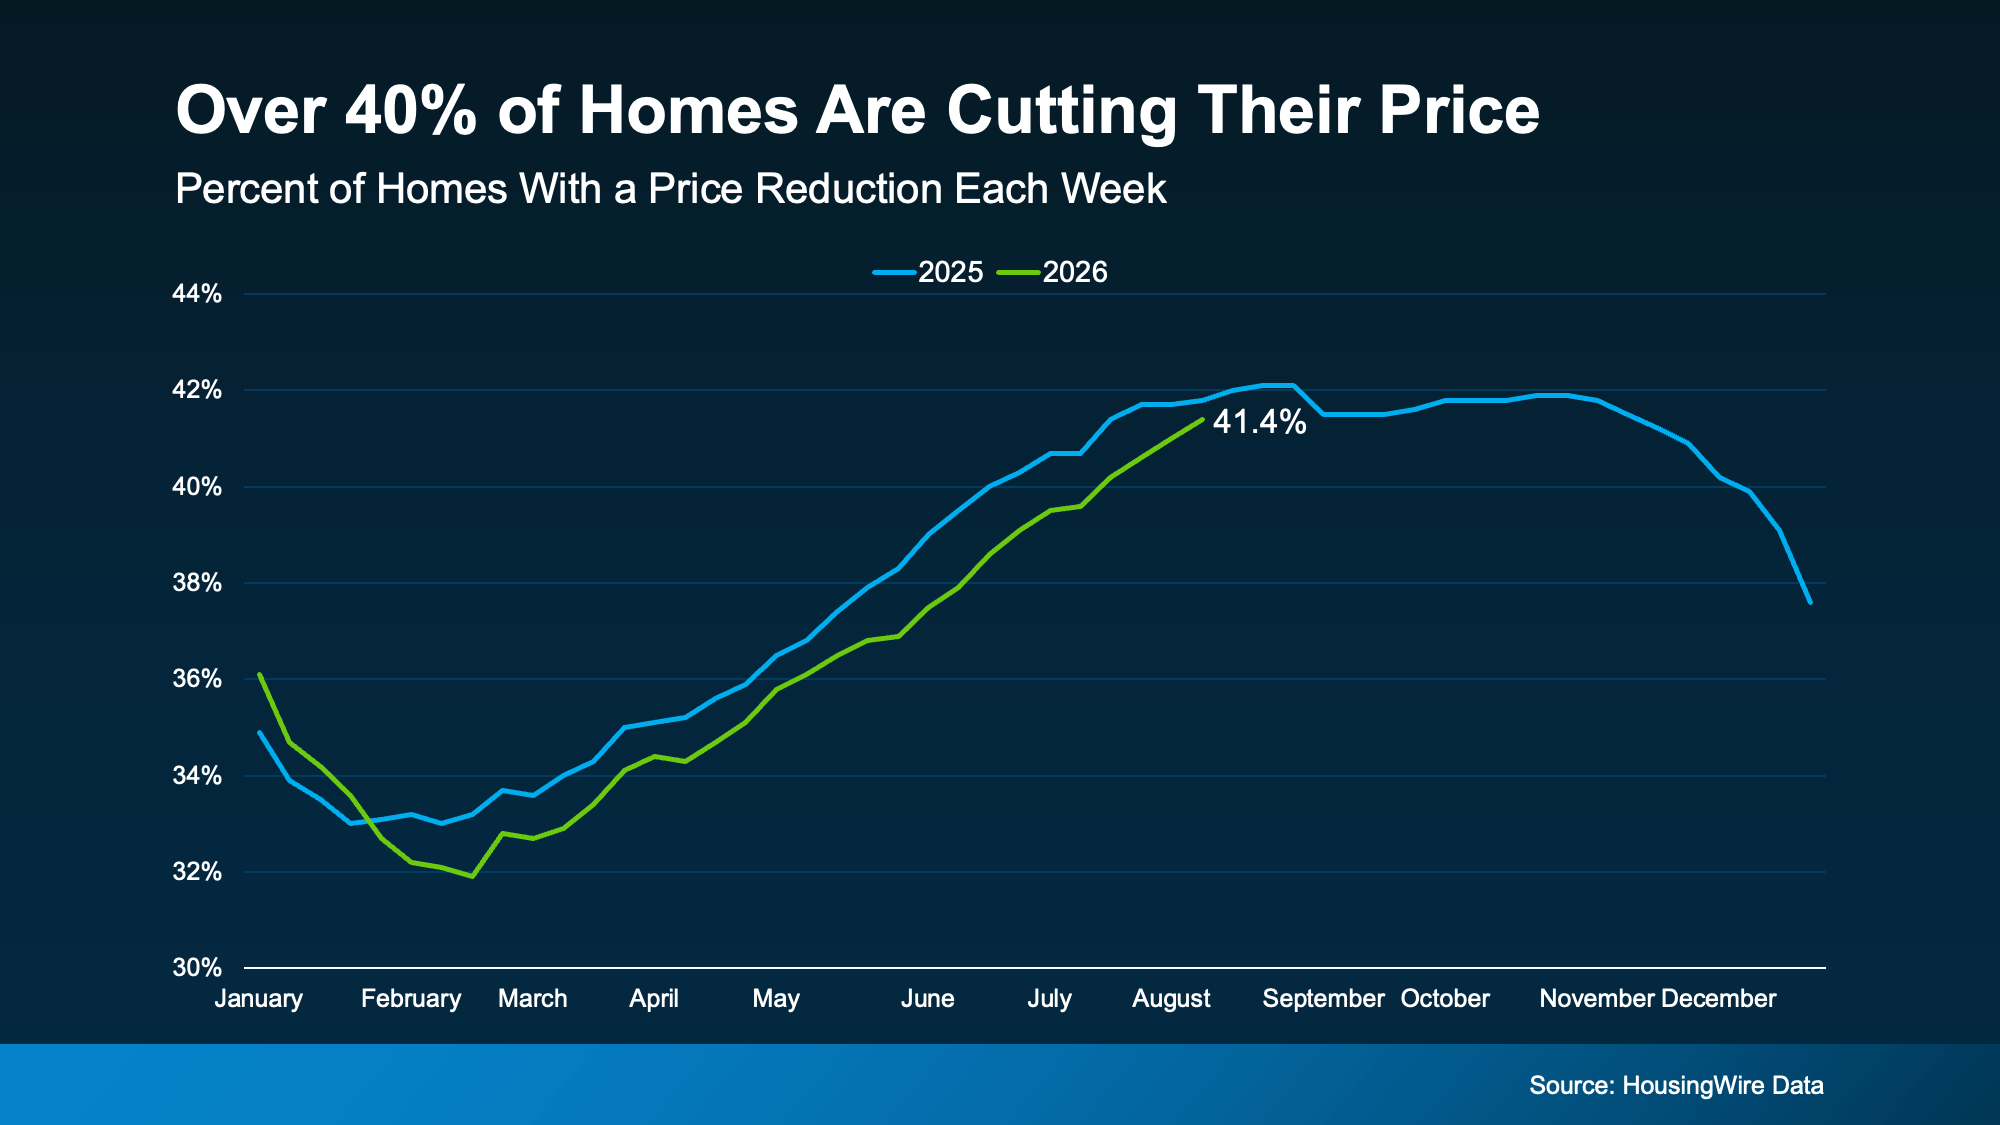
One of the clearest signs sellers are adjusting? Price cuts. HousingWire Data shows more than 40% of sellers are dropping this price.

That’s just slightly behind the volume we saw last year (see graph below):

a graph of a price reduction

That’s more than 4 out of every 10 homes listed. Think about what that means. That's thousands of sellers deciding they'd rather lower their asking price than keep waiting for someone willing to stretch their budget. 

They know that to sell, they have to be willing to do some give and take. And when no buyers are biting, they’re pulling their biggest lever to draw buyers back in – their price. As Danielle Hale, Chief Economist at Realtor.com, explains:

"This is a market where people are adjusting and showing up rather than giving up. Sellers are meeting the market with more realistic asking prices, which is helping deals get done."

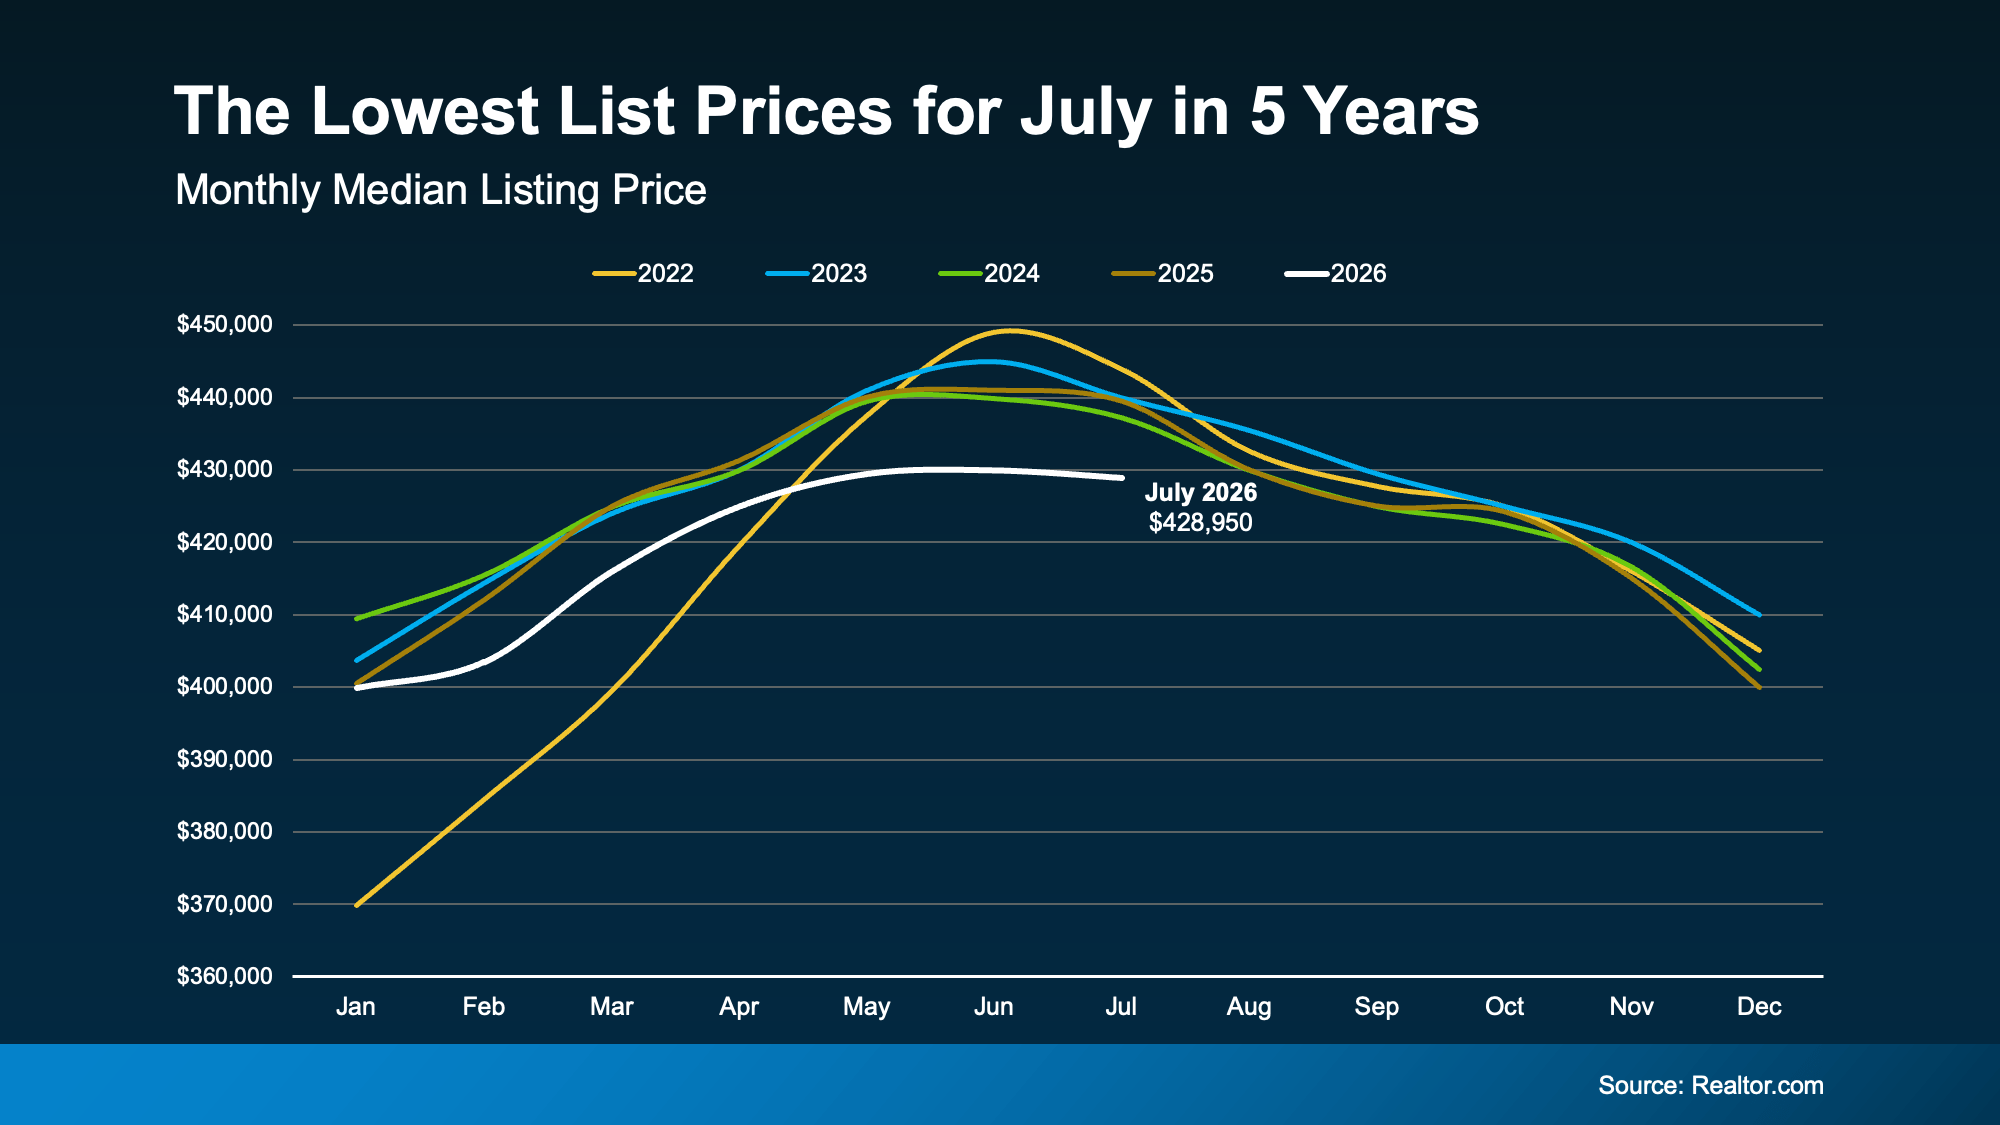
This July Saw the Lowest Median List Price for Any July in Five Years

What about the other 6 in 10 sellers? A lot of them started with a lower asking price to begin with rather than test the higher price and get crickets from buyers.

That may be why July 2026 had the lowest median list price of any July in the past five years, according to Realtor.com (see the white line in the graph below):

a graph of sales and prices

Now, that doesn't mean home values are falling or that everything's suddenly a steal. Prices are still above where they were before the pandemic. But what it does mean is this.

Sellers no longer banking on bidding wars or expecting buyers to pay whatever they ask. Instead, many are listing at prices that better reflect today's market from the very beginning. 

And honestly, whether they're pricing competitively from day one or adjusting after a few weeks on the market, the message for you is the same:

Sellers are more willing to meet you where you’re at.

Because in many markets throughout the country, you're not fighting over a house anymore. Sellers are fighting over you. And that’s information you can use to get a better deal.

Yes, affordability can be a real challenge. And the monthly payment you take on definitely does matter. But if you've been assuming everything is out of budget, there may be more wiggle room than you think.

Bottom Line

Right now, sellers are flexible on the price in ways they weren't before. Let’s take advantage of that flexibility.

You may be surprised by what's available – and how willing today's sellers are to work with buyers.

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.


Posted in Buying, Selling
Sept. 7, 2026

Thinking About Tapping into Your 401(k) To Buy a Home? Read This First.

Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you've caught the buzz and wondered whether that money could get you into a home faster, especially with affordability as tough as it is. 

Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything.

Why Dipping into a 401(k) Can Be Tempting

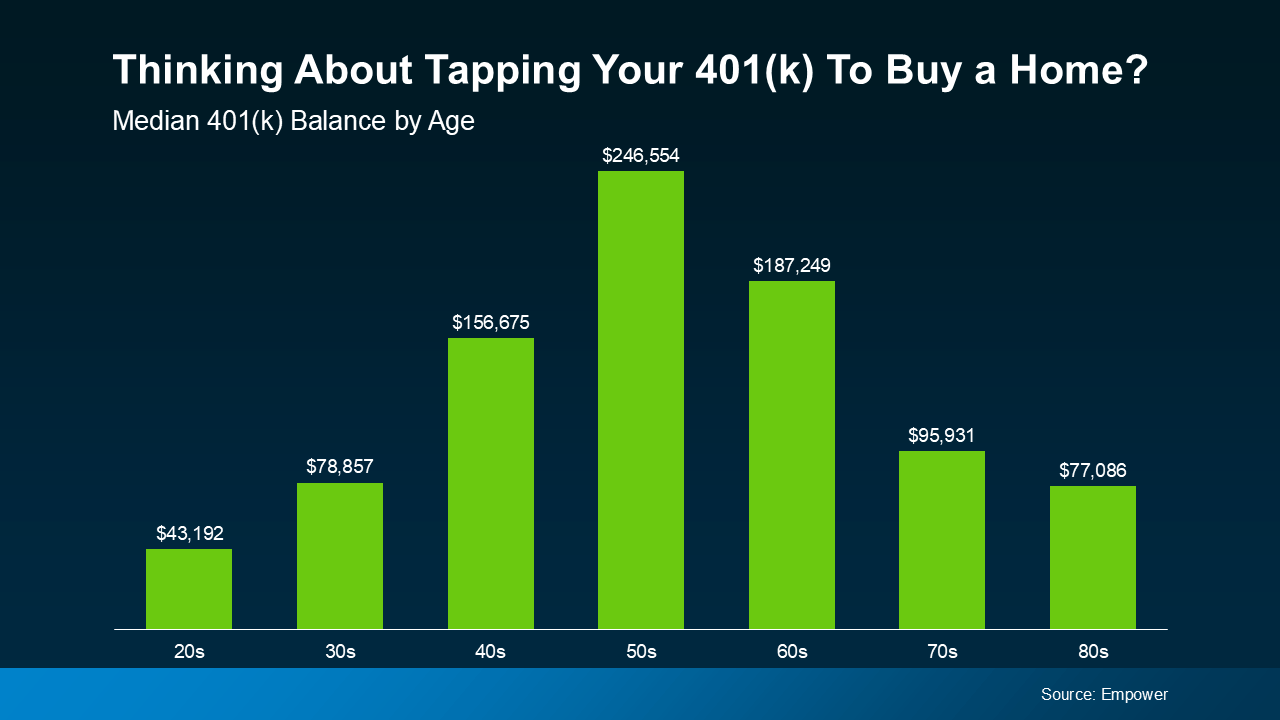
Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures (see graph below):

a graph of green barsAnd when you've got a good chunk saved and your dream home is right there, reaching for it can feel like an easy call.
But dipping into your retirement savings to buy a home could cost you a penalty and set back your finances later on. That's why it's a good idea to explore other options for your down payment first. As Redfin says: 

"If you’re struggling to save enough for a down payment, you may be wondering if tapping into your 401(k) is the right option. While it’s possible, doing so comes with significant risks, like early withdrawal penalties and lost investment growth."

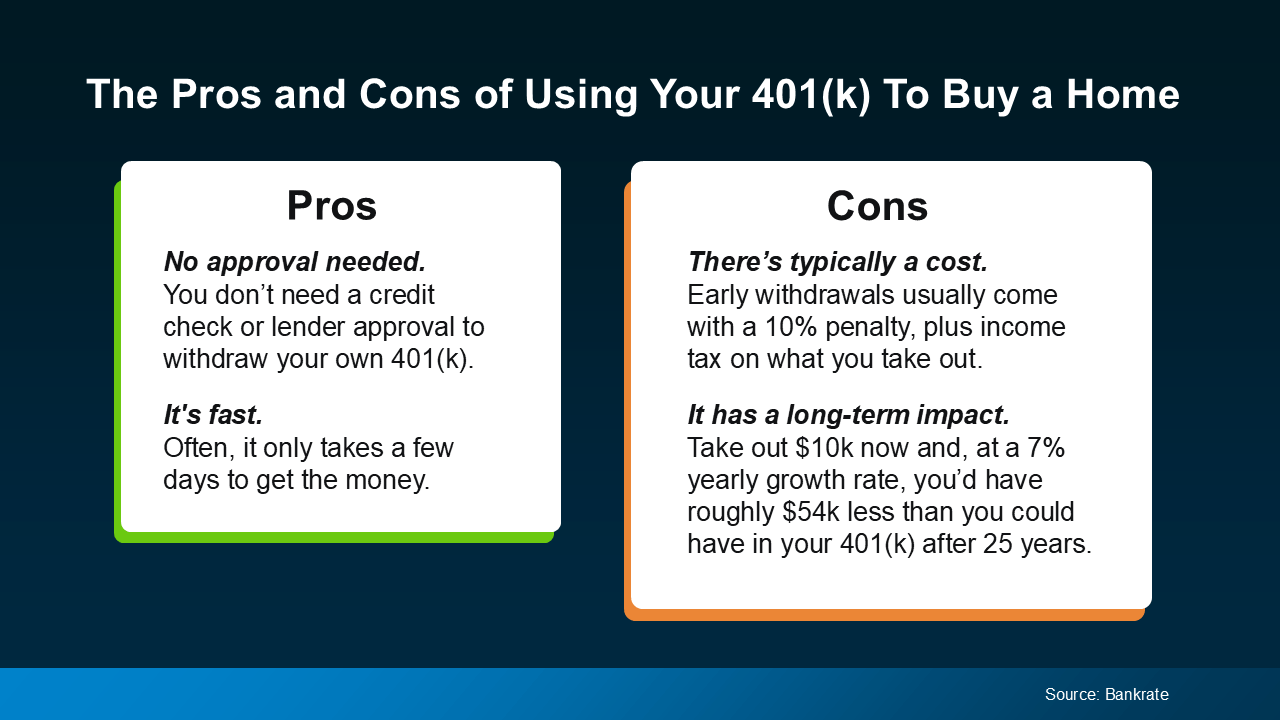
Before you decide, have a financial advisor help you compare the upsides to the risks. Bankrate points to a few of each (see visual):

a screenshot of a computer screen

Other Options Worth Exploring First

Your 401(k) isn’t the only way to finance a home purchase. Redfin outlines a few other options to look into before you decide what to do:

  • Low and No-Down Payment Loans: FHA loans, for example, allow qualified buyers to put down as little as 3.5% of the home's price, depending on their credit scores.

  • Down Payment Assistance Programs: Many national and local programs can help reduce what you pay toward your down payment or closing costs.

Make a Plan Before You Make a Move

No matter which route you take, talk with a financial expert first. The buyers who come out ahead build a solid plan with the right professionals before starting their journey to homeownership. As NerdWallet puts it:

"Even if you’re convinced a 401(k) loan is the way to go, it’s important to understand the risks at the outset."

Bottom Line

Affordability is definitely a challenge, but that doesn’t mean tapping your 401(k) is your only way in if you want to buy.

If you're considering using your 401(k) savings for a down payment, weigh all your options and talk with a trusted financial advisor before you make any decisions. They’ll help you make a plan to fit your goals and your budget. 


The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.


Posted in Buying
Sept. 7, 2026

Sellers Outnumber Buyers Right Now

Buying soon? You’ve got more pull than you might expect. Right now, there are more sellers than buyers on the market. And that means sellers know they’ll have to give a little to get their house sold. Exactly how much negotiating power you have depends on where you’re looking. So, let’s chat about how much power you have here, then turn it into a set of keys.


Posted in Buying, Selling
Sept. 7, 2026

Think New Homes Cost More? Not Right Now.

Most people think a newly built home costs more than an existing one. But right now, that’s actually backwards. Newly built homes are more affordable than existing ones in a lot of markets. And that’s because builders are cutting prices and stacking on incentives to try to keep their inventory moving.

Here’s why that’s really important for any would-be homebuyer to know.

Newly Built Homes Are the Better Deal Right Now

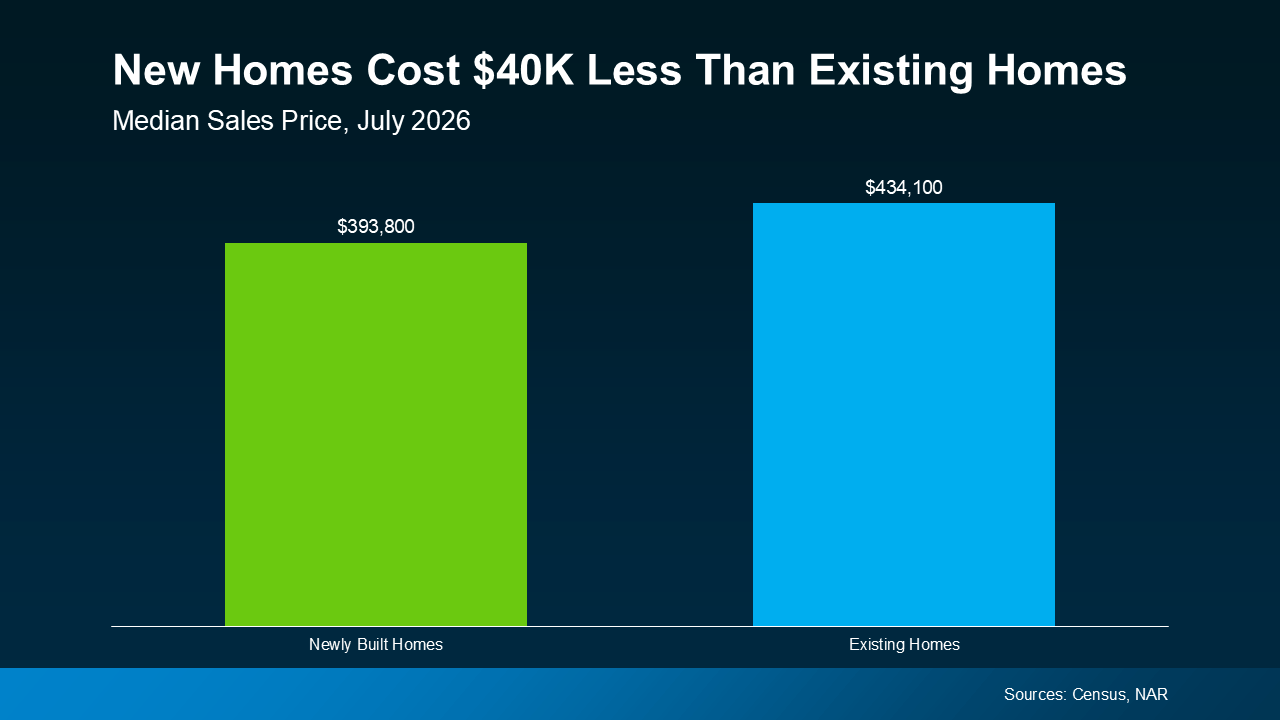
According to the latest data from the Census and the National Association of Realtors (NAR), a newly built home now typically costs about $40,000 less than an existing one (see graph below):

a graph of a house costBuilders aren’t like homeowners who can wait for the right offer. Unsold homes cost them money as long as they sit empty. So, builders cut prices and add incentives to keep them moving. That trend has carried into August. NAHB’s latest numbers:

  • 35% of builders cut prices, with an average reduction of 6%. 

  • 63% offered incentives like covering closing costs or buying down your mortgage rate. 

And those incentives can make a real dent in what you pay upfront and every month after. Plus, since everything is new and many builders offer warranties, you could save on home maintenance costs too. And with affordability where it is, every dollar counts.

So, don’t cross new builds off your list just yet. Yes, you may think they cost more, but that’s not always the case. 

If you can get brand-new everything for less than buying an existing home, isn’t that at least worth looking into? 

Don’t Let the Builder Pick Your Teammate

But before you tour a single model home, there's one thing worth figuring out first – who's actually working for you once you walk through that door.

That friendly rep in the builder's sales office works for the builder, not you. Their job is to protect the builder's bottom line, not yours. Your own agent flips that. 

They know the local market, so they can tell you if the builder's price and upgrades stack up against other options nearby. They'll negotiate on your behalf, whether that's a lower price, free upgrades, or a rate buydown. 

A good agent will also push for a home inspection. Builders won’t always bring it up, but it’s a step you shouldn’t skip, even on a new build. And your agent will be in your corner, so you know what you’re buying and get the best deal possible. 

Bottom Line

New homes may actually cost less than an existing home right now. And that’s opening up a window for you to get brand-new for less.

If you want a list of new home communities near you that are currently offering incentives or doing price cuts, let’s connect. That way you have someone in your corner helping you get the best deal possible.  

The information contained, and the opinions expressed, in this article are not intended to be construed as investment advice. Keeping Current Matters, Inc. does not guarantee or warrant the accuracy or completeness of the information or opinions contained herein. Nothing herein should be construed as investment advice. You should always conduct your own research and due diligence and obtain professional advice before making any investment decision. Keeping Current Matters, Inc. will not be liable for any loss or damage caused by your reliance on the information or opinions contained herein.


Posted in Buying